FlyExclusive posted another double-digit revenue increase, steady increases in positive EBITDAR and EBITDA, and a significantly narrowed net loss in its Q3 financials this morning.
It also struck a deal with Fly Alliance, a top-15 charter operator.
FlyExclusive Q3 financials
For FlyExclusive, Q3 revenues rose 21% year over year to a record $111.1 million from $92.1 million.
Flights increased to $103.9 million from $86.7 million year over year.
MRO revenues increased to $4.3 million from $3.1 million on a like-for-like basis.
Fractional ownership purchase price went from $1.2 million to $4.3 million.
Gross profit rose 95% to $24.6 million from $12.6 million.
Adjusted EBITDA was $5.1 million, up from negative $1.9 million a year ago, marking the third positive result over the past four quarters and a quarter-to-quarter increase of $1.3 million.
Adjusted EBITDAR jumped from $2.8 million to $9.4 million.
For the first three quarters, overall revenues were up to $318.5 million from $271.6 million a year ago.
Q3 Financial and Operating Results
| Metric |
Three Months Ended September 30, 2026 |
Three Months Ended September 30, 2025 |
Change |
| Revenue |
$111.1M |
$92.1M |
+21% |
| Gross profit |
$24.6M |
$12.6M |
+95% |
| Gross margin |
22.2% |
13.7% |
+850 bps |
| Adjusted EBITDA |
$5.1M |
$(1.9)M |
+$7.1M |
| Adjusted EBITDAR |
$9.4M |
$2.8M |
+$6.6M |
| Total flight hours |
19,660 |
18,289 |
+7% |
| Ending aircraft on certificate |
73 |
90 |
(19%) |
| Dispatch availability |
58.2% |
48.9% |
+930 bps |
Source: FlyExclusive
For the first three quarters, flight revenues were up to $300.3 million from $255.2 million a year ago.
Year-to-date Adjusted EBITDA rose from-$13.5 million to $8.6 million.
Adjusted EBITDAR for the year spiked from $1.5 million for the first three quarters of 2025 to $20.9 million year-to-date in 2026.
Fuel costs were up 13% year over year, and the company paid an average of $7.02 per gallon. However, the company said the impact on the bottom line was minimal, as it mainly passed the higher costs on to wholesale and retail customers.
FlyAlliance pact
In its 10-Q filing (downloadable at the bottom of this story), FlyExclusive said it had entered into an Aircraft Management Services Agreement with Fly Alliance.
The deal was signed yesterday, according to the documents filed with the SEC.
FlyExclusive will provide aircraft management, maintenance, finance, accounting, and treasury management services to Fly Alliance.
FlyExclusive “will be entitled to retain the excess of revenue collected over expenses in connection with its delivery of services under the deal.
It also gets a share of Fly Alliance’s profit.
Fly Alliance’s current owner, Christopher Tasca, and former owner Kevin Wargo have been involved in an increasingly messy split.
The Federal Aviation Administration currently lists 18 aircraft as available for charter on the Fly Alliance certificate sold to Wargo.
A spokesperson tells Private Jet Card Comparisons that more details will be released after the market closes today.
Financial, operational gains
In a call with investors, Chairman and CEO Jim Segrave said the most impressive part is the company’s improved operational performance.
“We delivered these results, as we have consistently done to this point, with a much smaller fleet,” he said, continuing, “We flew more hours, generated more revenue, and retained more of that revenue as gross profit, on a fleet that is 19% smaller than it was a year ago.”
Segrave told analysts, “The improvements we have made to the fleet and the way we operate are showing up in the economics of the business.”
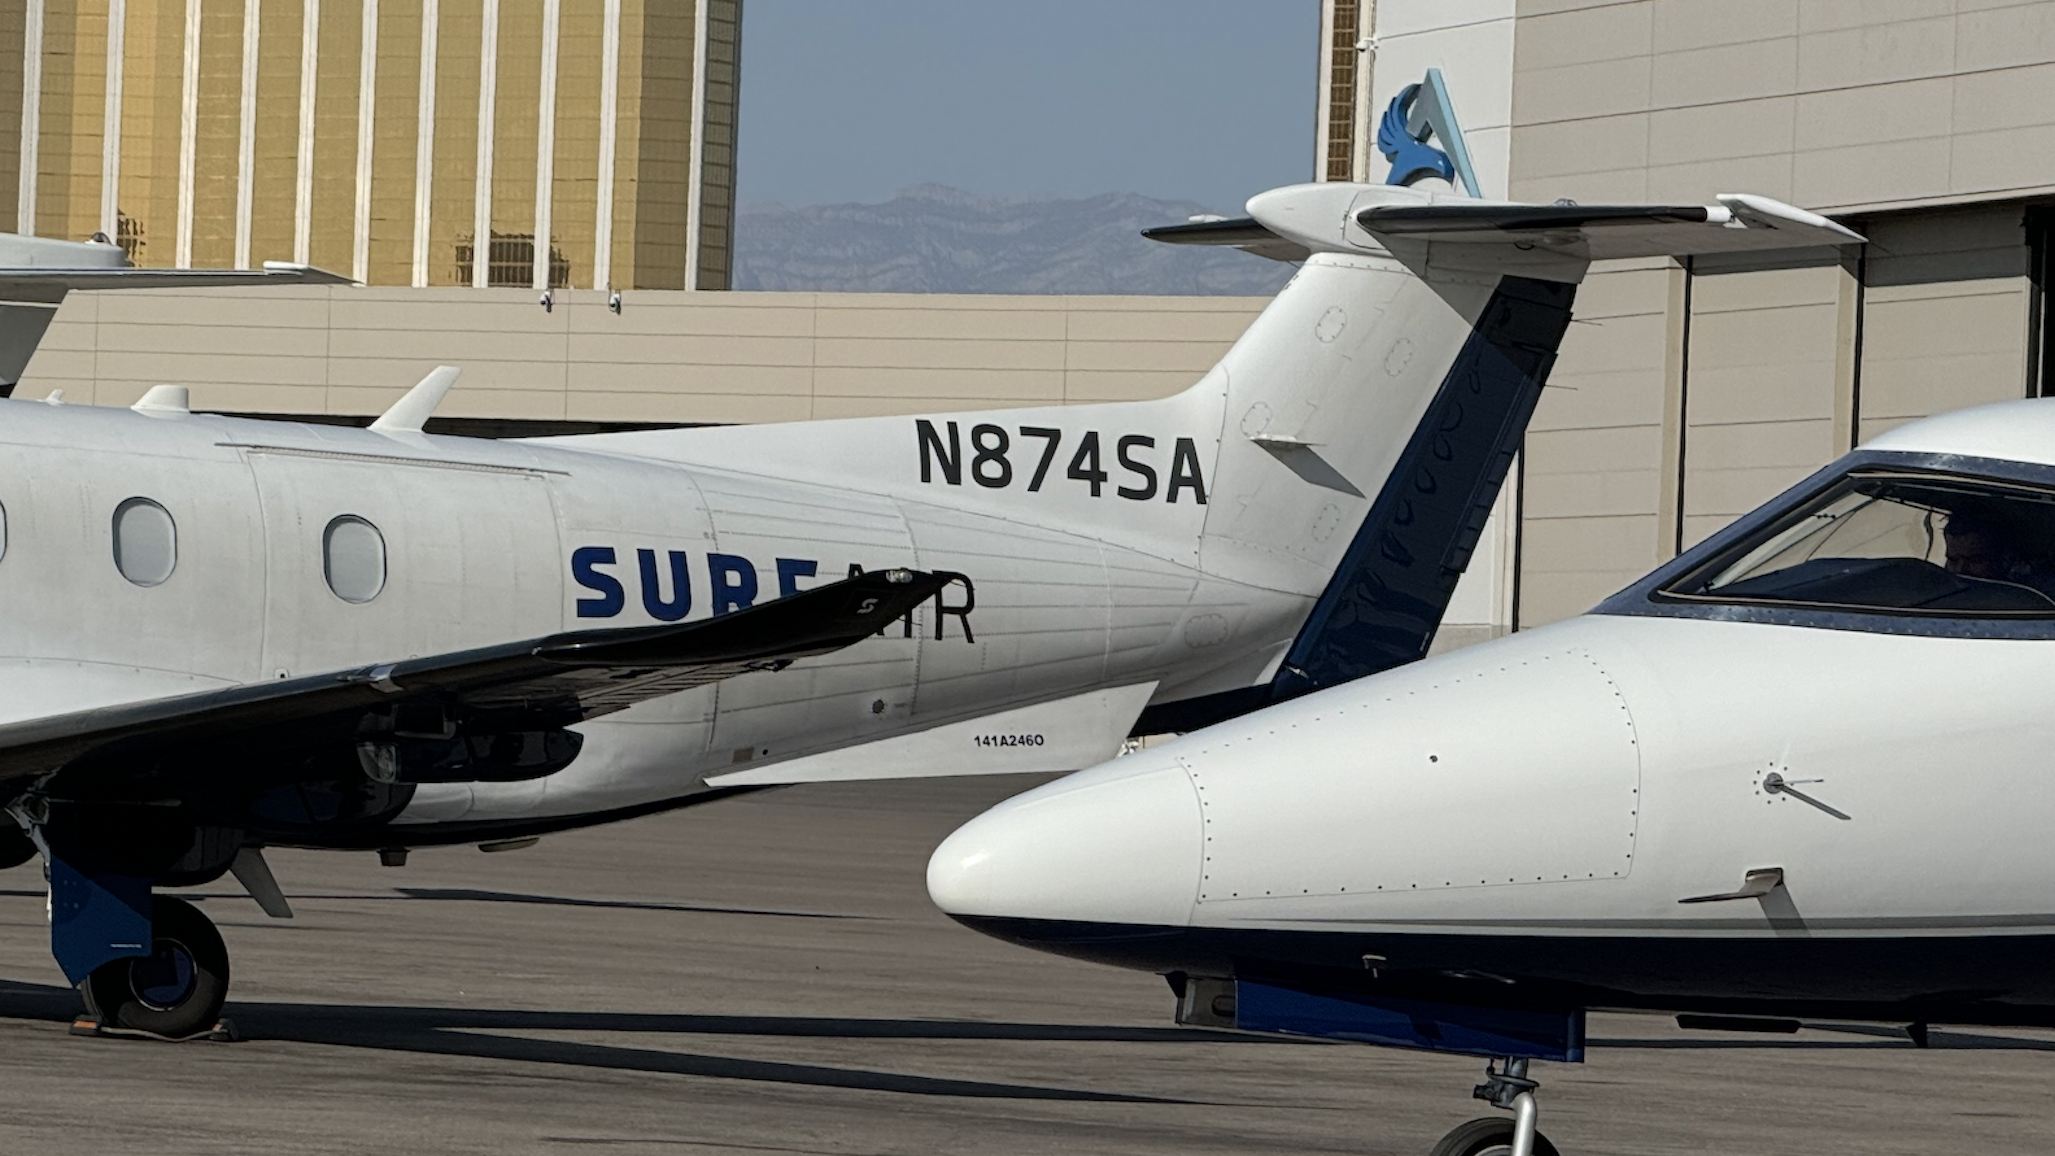
From Q1 2024 through the end of this year’s Q3, the company has exited 35 of 37 underperforming legacy aircraft that dragged earnings and affected both productivity and reliability.
The exited aircraft were causing $3 million in monthly operating losses, Segrave said.
Replacing them with more modern aircraft boosted dispatch availability by 19% to 58.2%, up from 48.9% a year ago.
World Travel Awards recently tabbed FlyExclusive as the top charter operator in North America.
Investments
Segrave said investment in maintenance, including remote units, is paying off.
FlyExclusive has deployed 14 Mobile Service Units across strategic geographic regions.
The units enable aircraft maintenance away from its Kinston, North Carolina-based operations.
Executives estimate a 50% cost savings compared with external providers while supporting faster aircraft return-to-service.
Segrave told listeners, “The capabilities we have built in Kinston, together with our mobile service units, give us greater control over maintenance costs and turnaround times. Doing more work where our aircraft are located helps us return them to service faster and reduces our dependence on outside providers.”
The company’s founder said the turnaround is not finished.
He said:
‘We still have more work to do. We reported a GAAP net loss of approximately $13 million for the quarter. About $5.5 million of this loss relates to GAAP depreciation that, in our view, does not reflect the actual market depreciation incurred. In fact, we believe our aircraft and assets are worth materially more than their carrying value on the balance sheet. From a cash perspective, we ended the third quarter with $19.6 million in cash – up $5.3 million and 37% over the second quarter – and we expect to continue building cash in the fourth quarter. Positive Adjusted EBITDA is an important measure of our progress, but our objective is to build a business that produces durable earnings and cash flow. And to that end, we expect to deliver positive operational cash flow in the fourth quarter.’
The company is also keeping costs in check. It is also betting on technology.
“Revenue grew faster than overhead, although we still have an opportunity to improve this relationship as we scale, through increased technology usage,” Segrave said. “Our task now is to carry the operating improvement through overhead, financing costs and capital requirements into durable earnings and cash flow.”
Customer Growth
The company also saw a boost with its two key programmatic offerings.
Jet Club sales reached $38.6 million during the quarter, up 22% year over year.
New jet card sales were up 43%.
Renewals increased 11%.
Fractional sales rose about 22% to $ 16.8 million.
Members contributing revenue increased from 1,168 to 1,252 year over year at the end of Q3, while Active members were flat, going from 1,088 to 1,086.
Meanwhile, the company’s wholesale business has remained a growth engine.
Wholesale sales for 2026 exceeded full-year 2025 sales by mid-October, according to Segrave.
Wholesale revenue was 51% in 2025, down from 91% in 2021 as FlyExclusive rolled out its Jet Club and then fractional ownership.
Looking ahead.
While the industry has slowed since the beginning of summer, Segrave predicts FlyExclusive will finish the year strong.
Segrave said, “We are going to set records for the company at every level over the next 60 days. It is so much fun to be a part of a winning team.”
“We expect to break that record (third quarter revenue) in the fourth quarter,” Segrave said, continuing, “Our utilization rate on our aircraft this quarter-to-date is now approaching 100 hours per plane, an industry-leading level, and we are confident that with our new flight management software we just launched a few weeks ago, deeply leveraging artificial intelligence, we can increase utilization another 20%.”
In October, FlyExclusive flew nearly 7,300 flight hours.
During the third quarter, the company averaged 6,553 flight hours per month.
Total flight hours were up year-to-date from 54,236 to 58,237 even though aircraft on its certificate dropped from 90 to 73.
Segrave said:
‘Revenue per SG&A employee will continue to increase. Gross profit set a record in the 3rd quarter, and it will increase further. Pilot compensation continues to increase with the higher utilization, setting industry-leading pay levels for our pilot team. Wholesale sales exceeded full-year 2025 performance, with the busiest 75 days left in 2026. And the retail sales team is performing stronger than ever.’
CFO Brad Garner told analysts, “Our focus now is on converting that progress into stronger cash generation and returns on the capital invested in the business.
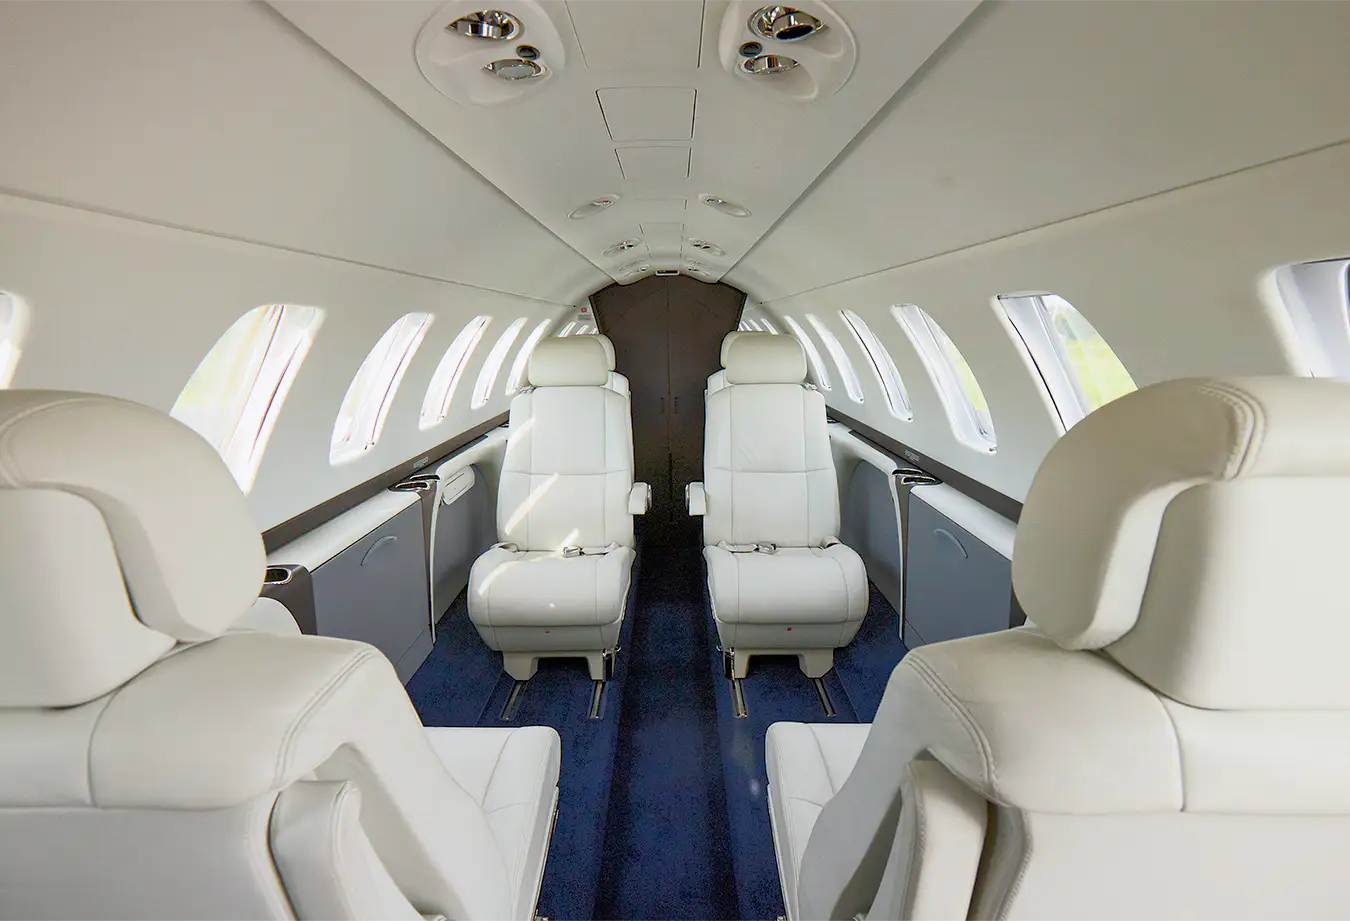
Garner said its recent Jet.AI transaction “brought aircraft deposits supporting three new CJ3+ aircraft expected to deliver in early 2027.”
He added, “As those aircraft are delivered, together with our continued investment in the fleet, we expect them to expand our capacity with newer, more efficient aircraft and support further growth in flight hours and utilization.”
Debt reduction, cash
FlyExclusive ended the third quarter with $19.6 million in cash and cash equivalents, up from $14.2 million on June 30, 2026, but down from $29.3 million at the end of 2025.
Deferred revenue, mostly prepaid jet cards and deposits for fractional shares, was $139.8 million, up slightly from $135.9 million.
Long-term notes payable were approximately $136.0 million at September 30, compared with $165.4 million the prior year, a reduction of approximately $29.5 million, or 18%.
Garner said, “Since the beginning of 2025, we have reduced long-term notes payable by approximately $96 million, and debt balances subject to lender covenant waivers declined from $8.9 million at the end of 2025 to zero. We remain extremely focused on de-levering the business to strengthen the balance sheet and provide operational flexibility while balancing the business’ liquidity needs.”
Garner added, “The levers driving these results – dispatch availability, utilization, vertical integration, and SG&A leverage – still have substantial runway, and our focus is on converting those operating gains into stronger cash generation and returns as we scale.”
FlyExclusive ended 2025 as the fifth-largest U.S. private jet operator based on fractional and charter flight hours.
FLYX opens trading this morning at $1.09. Its 52-week price has ranged from $0.80 to $8.88.
DOWNLOAD: FlyExclusive Q3 2026 Financials