Over the past month, private jets in North America recorded a positive year-over-year gain.
Last month, ARGUS analysts predicted a slight year-over-year decrease of about 0.1%.
This would have been the first negative year-over-year result in 2026.
However, the year-over-year increase in September was about 0.9%.
ARGUS TRAQPak analysts expect this positive trend to continue into October, predicting a 1.1% year-over-year increase.
Travis Kuhn, Senior Vice President at ARGUS, spoke with Private Jet Card Comparisons about the positive growth of the private aviation industry in North America.
Kuhn stated:
‘September’s results were surprising to us as all indicators showed a decline in activity when the month began. Fortunately, that forecast didn’t turn out to be correct, and activity was positive. This continues to point to the strength and resiliency of the business jet market in North America & abroad. We do have concern areas, but overall demand has held firm heading into what is usually a busy Q4 season for activity.’
Private jet flight activity in September exceeded expectations overall.
Private Jet Growth
According to ARGUS TRAQPak, private aviation’s aircraft categories saw mixed results.
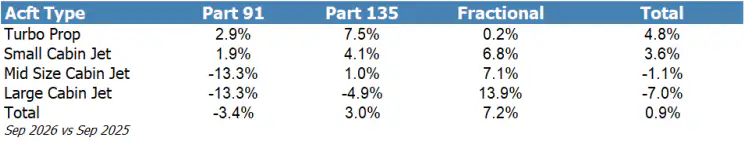
Turboprops posted the largest year-over-year increase, with 4.8% more flights than last September.
The small cabin jet market also grew, with 3.6% more flights year over year.
However, the midsize jet market saw a slight decrease of about 1.1%.
Additionally, the large cabin jet market saw the largest year-over-year decrease. This segment recorded 7.0% fewer flights than last September.
September 2026 Private Jet Flight Activity
Like the aircraft categories, the various business segments also saw mixed results.
Fractional operations increased about 7.2% year over year. This was the largest growth among business segments.
Part 135 operations also remained positive, recording 3.0% more flights than last September.
However, the Part 91 category fell year over year, with 3.4% fewer flights.
![]()
Additionally, September private jet flight activity remained positive month over month. Overall, September recorded 1.9% more flights than August.
This led to an average flights-per-day increase of about 5.3%, since September had one fewer day than August.
In North America, six of the eight major regions recorded a monthly increase in flight activity.
The Southwest and the South each recorded double-digit month-over-month jumps.
The Northeast saw the largest decrease of about 16.9%, followed by the Caribbean, which saw 14.4% fewer flights.
Fractional Operators
Fractional operations increased about 7.2% year over year.
This was largely led by large-cabin jets, which recorded 13.9% more flights than last September.
However, both the midsize cabin jet segment and the small cabin jet market saw significant growth, with each respectively recording a 7.1% and a 6.8% jump
All major categories remained positive, yet the turboprop segment saw the slightest growth. That segment saw only 0.2% more fractional flights year over year.
Part 135 Operators
Part 135 operations also remained positive, posting 3.0% more flights year over year.
Most segments in this category grew, with the turboprop segment posting the largest year-over-year jump of about 7.5%.
Both the midsize and small cabin jet markets also grew. The midsize segment saw a 1.0% jump, while the small cabin segment saw 4.1% more Part 135 flights year-over-year.
The only aircraft category to see a year-over-year drop is the large cabin jet market, which saw 4.9% fewer flights.
Part 91 Activity
Part 91 operations fell about 3.4% year over year.
This was largely due to massive drops in both the large cabin jet segment and the midsize cabin jet market. Each aircraft type saw 13.3% fewer flights in Part 91 operations.
The small cabin jet market saw the smallest year-over-year increase, recording 1.9% more flights than last September.
Additionally, the turboprop market saw 2.9% more Part 91 flights, the largest jump in the category.