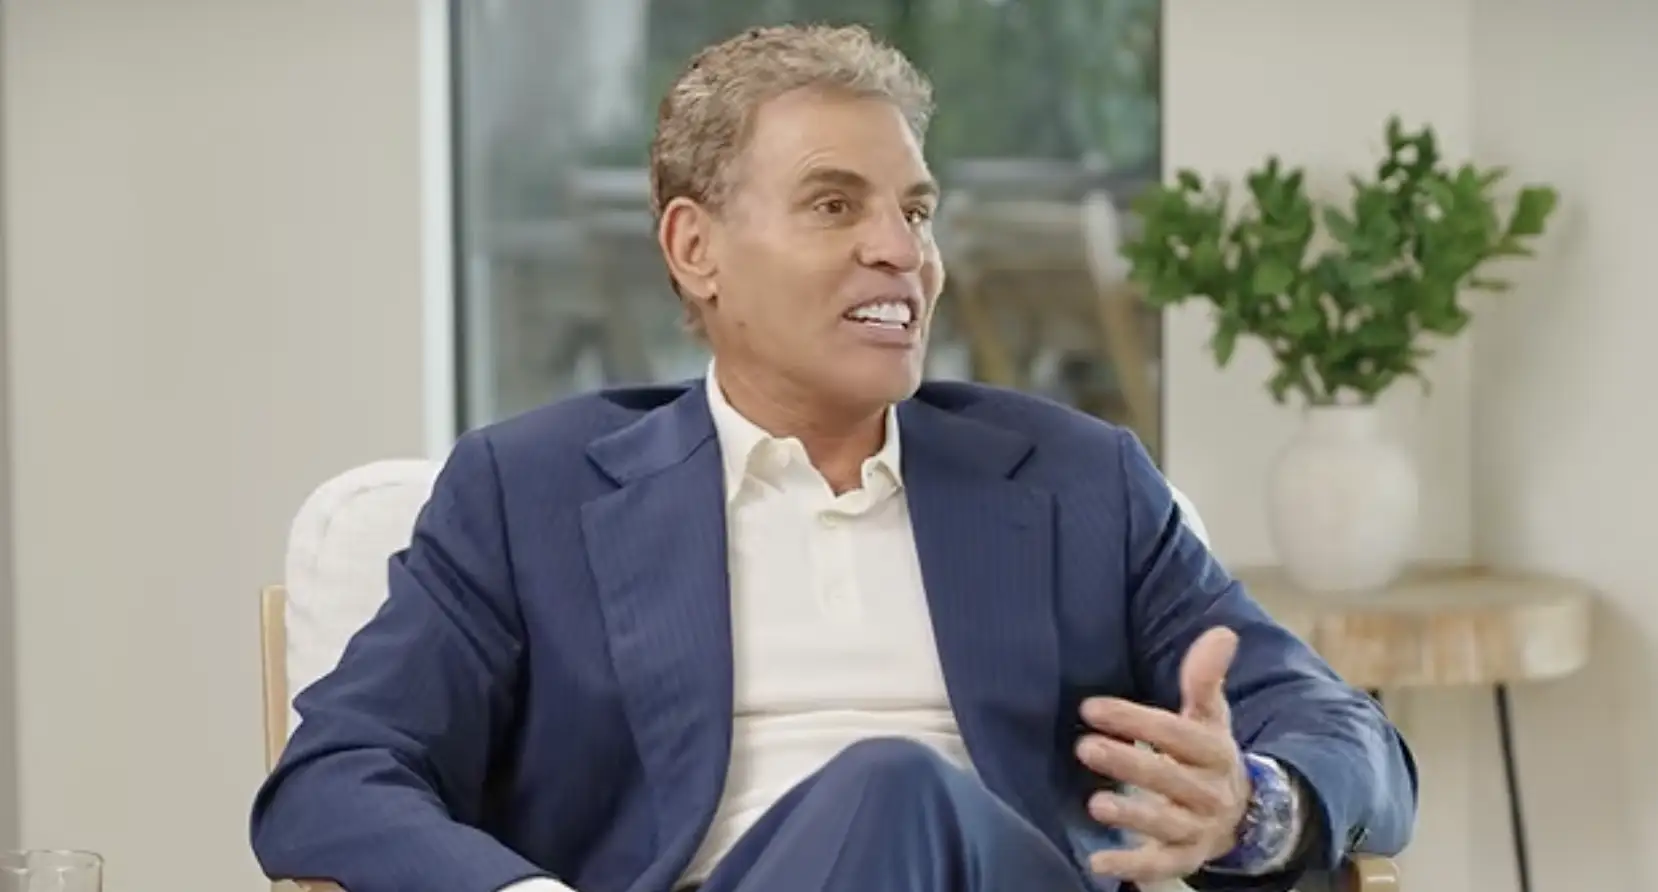
Flexjet Chairman Kenn Ricci built one of private aviation’s largest businesses partly through acquisitions, mergers, and investments and says some of his early deals opened the door for private equity.
However, on the David Senra podcast, Ricci, who oversees fractional Flexjet, jet card seller Sentient Jet, on-demand broker FXAir, and a host of business aviation companies, says he no longer advocates M&A or PE.
Mergers, no thanks
Private aviation mergers have been commonplace as companies seek to consolidate a fragmented industry.
“I hate (mergers) for me, because for me, I think they’re a sign of weakness, because you can’t build your business on your own,” Ricci told Senra.
He questions whether companies need acquisitions to gain market share when they could instead invest the same capital in their existing businesses.
“Do you really need to spend 12, 10 times cash flow to grab the market? Would you invest that money yourself and grab the market share, or do you not have a good enough product to do it?”
Ricci believes companies often underestimate how hard it is to integrate different corporate cultures.
“I would tell you 90% of the time, you could probably do this yourself without the acquisition,” he said.
He added that integrating a workforce representing 10% of existing employees might be manageable, but adding 30% or 40% makes cultural integration nearly impossible.
His own experience helps explain that perspective.
After launching Flight Options in October 1998, Ricci generated $100 million in sales during its first three months and another $400 million the following year.
However, the dot-com downturn exposed cash-flow challenges, prompting a 50/50 merger with Raytheon’s fractional ownership business, Travel Air.
The merger ultimately led to Raytheon buying Ricci out in 2002.
He described losing control of Flight Options as the worst day of his life.
Ricci subsequently reacquired Flight Options in December 2008, paying $15 million in cash and signing a $27 million personal note while assuming additional liabilities.
He later acquired Flexjet from Bombardier for $180 million, beginning another lengthy integration process involving two companies with different cultures and labor relationships.
READ: Private Aviation Deal Book – List of M&A
Private equity
Ricci was equally critical of private equity, particularly its influence on the FBO business.
He contrasted publicly traded companies, which face disclosure requirements covering financial performance and other corporate policies, with private equity firms.
“Private equity has to disclose none of that. They are solely based upon a return to investors, so they’re solely about greed,” he said.
Ricci argued that private equity investors have consolidated the FBO market and increasingly focused on extracting revenue from aircraft owners.
“They’ve taken an industry and just tried to monopolize it. It’s a duopoly now in the FBO industry,” he said.
However, Ricci acknowledged his own role in the consolidation.
After leaving Flight Options, a non-compete agreement prevented him from operating a competing aviation business but allowed investments in FBOs.
In 2005, he partnered with Allied Capital to acquire Mercury Air Centers for $80 million.
Ricci said the company had approximately 18 locations when he acquired it.
After roughly doubling its size, the partners sold Mercury to Macquarie in 2007 for $615 million.
Ricci owned 20% of the business, while Allied Capital held 80%.
“I started the industry, so in many ways, I created this monster,” he said, referring to FBO consolidation.
He noted that FBO acquisitions that previously commanded approximately six times EBITDA can now trade at 15 to 20 times EBITDA.
The importance of the balance sheet
Another recurring theme was Ricci’s belief that financial strength, rather than reported earnings, determines success in capital-intensive aviation businesses.
“In capital-intensive industries, particularly aviation, the balance sheet is the whole game. It’s not the income statement. It’s the balance sheet,” he said.
“Forget income, forget EBITDA. It’s free cash flow and how strong is your balance sheet.”
Ricci said he learned that lesson after Flight Options experienced explosive growth following Warren Buffett’s $750 million acquisition of NetJets in 1998.
Before Buffett’s purchase, Ricci struggled to secure the $30 million to $40 million needed to launch his competing fractional ownership business using pre-owned airplanes.
After Buffett validated the fractional model, Ricci secured nearly $300 million in debt financing.
The experience reinforced another lesson that shaped his investment strategy: access to capital can determine whether an otherwise successful aviation business survives.
You can listen to the full interview here.